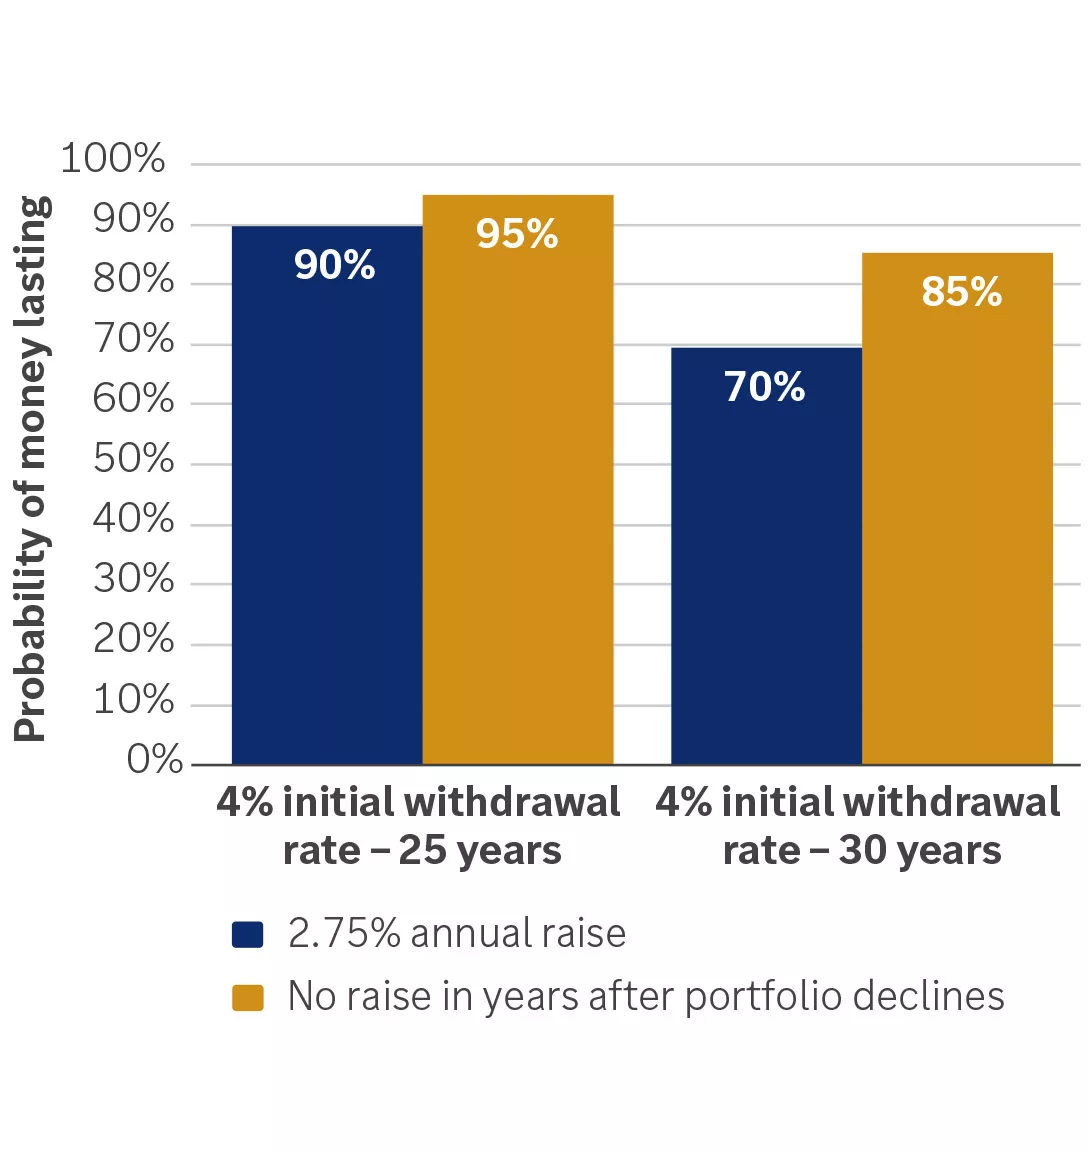
The chart illustrates the impact of avoiding annual raises in portfolio withdrawals after years when the portfolio’s value declines. For investors who start with a 4% withdrawal rate, the portfolio has a 90% chance of lasting 25 years with a 2.75% raise every year compared with a 95% chance if there’s no raise following years when the portfolio’s value declines. It has a 70% chance of lasting 30 years with a 2.75% raise every year, compared with an 85% chance if there’s no raise following years when its value declines.
The chart illustrates the impact of avoiding annual raises in portfolio withdrawals after years when the portfolio’s value declines. For investors who start with a 4% withdrawal rate, the portfolio has a 90% chance of lasting 25 years with a 2.75% raise every year compared with a 95% chance if there’s no raise following years when the portfolio’s value declines. It has a 70% chance of lasting 30 years with a 2.75% raise every year, compared with an 85% chance if there’s no raise following years when its value declines.
Important information:
This information is for educational and illustrative purposes only and should not be interpreted as specific investment advice. Investors should make investment decisions based on their unique investment objectives and financial situation.
Edward Jones, its employees and financial advisors are not estate planners and cannot provide tax or legal advice. You should consult your estate-planning attorney or qualified tax advisor regarding your situation.
Edward Jones is a licensed insurance producer in all states and Washington, D.C ., through Edward D. Jones & Co., L.P., and in California, New Mexico and Massachusetts through Edward Jones Insurance Agency of California, L.L.C.; Edward Jones Insurance Agency of New Mexico, L.L.C.; and Edward Jones Insurance Agency of Massachusetts, L.L.C. California Insurance License OC24309.