Higher bond yields could set the stage for stronger returns ahead
Key takeaways
- Bond yields have risen as expectations for Fed tightening have grown, inflation concerns have increased, and government and corporate bond issuance has expanded.
- Resilient economic growth, persistent fiscal deficits, and lingering inflation risks could keep yields elevated and make a sustained decline unlikely.
- Higher starting yields improve bonds' longer-term return potential, primarily through greater income. However, further increases in yields could create some volatility.
Bond yields have risen
Bond yields have risen from their February lows, bringing the 10-year Treasury yield toward the upper end of our expected 4.5% - 5.0% near-term range. The increase likely reflects a combination of factors:
- A less accommodative Fed outlook - Expectations for Fed rate cuts have given way to the likelihood of rate hikes. This shift has pushed yields higher, particularly at the short end of the curve, which is more sensitive to changes in monetary policy expectations. A resilient labor market gives policymakers greater flexibility to keep rates elevated while focusing on inflation.
- Higher inflation - Inflation has picked up, partly because of rising energy costs. Market-based inflation expectations, an important component of bond yields, have also moved higher.
- Larger bond issuance – Treasury issuance has increased as the federal government finances persistent deficits. Corporate bond issuance has also grown, partly reflecting increased borrowing to fund AI-related investment. Greater supply can place upward pressure on yields as issuers compete for investor demand.
- Rising global yields – Government bond yields have increased across several major markets, reflecting many of the same monetary-policy, fiscal and inflation pressures affecting the U.S. In particular, higher Japanese government bond (JGB) yields effectively establish a floor for global yields, with the 10-year JGB yield recently reaching 3.0%, its highest level in 30 years.
Resilient economic growth, persistent fiscal deficits, and ongoing inflation risks generally place upward pressure on yields. Together, these forces make a large and sustained drop unlikely, in our view. However, yields could fall if economic growth slows or inflation eases more quickly than expected.
Stronger fixed-income returns could lie ahead
Higher yields mean bonds generate more income, historically the primary driver of bond returns over the long term. Because Treasury yields serve as a benchmark for much of the U.S. investment-grade bond market, today's elevated starting yields should provide a firmer foundation for solid returns in the years ahead, as shown in the chart below.
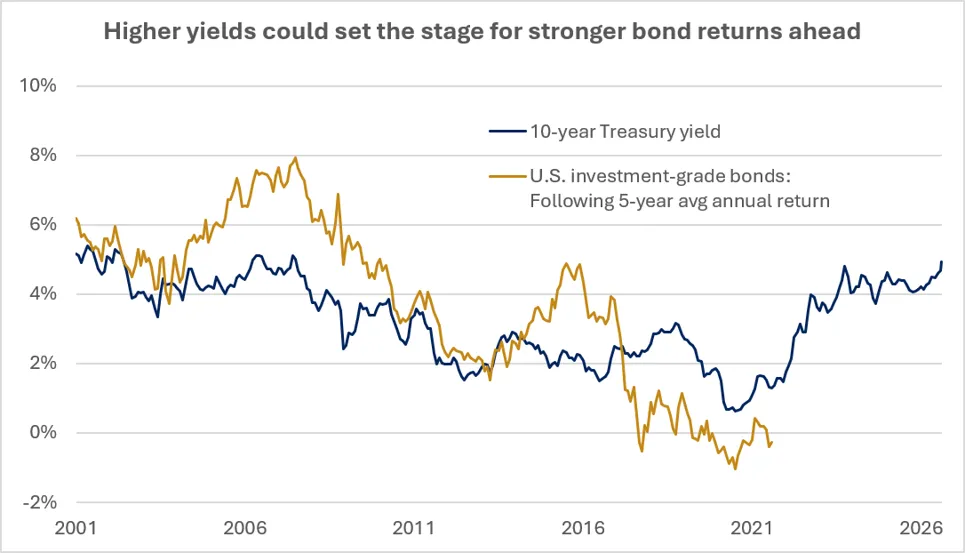
The chart shows that higher starting yields have historically been associated with stronger subsequent bond returns. U.S. investment-grade bonds represented by the Bloomberg U.S Aggregate Bond Index.
The chart shows that higher starting yields have historically been associated with stronger subsequent bond returns. U.S. investment-grade bonds represented by the Bloomberg U.S Aggregate Bond Index.
Most of the return contribution is likely to come from income rather than substantial price appreciation. Higher income also provides a larger cushion against modest increases in yields, helping investors absorb some near-term price volatility. Overall, higher starting yields improve the longer-term risk-reward profile of fixed income, even if they do not necessarily signal an immediate peak in rates.
Brian Therien
Brian Therien is a Senior Fixed Income Analyst on the Investment Strategy team. He analyzes fixed-income markets and products, and develops advice and guidance to help clients achieve their long-term financial goals.
Brian earned a bachelor’s degree in finance from the University of Illinois at Urbana–Champaign, graduating with honors. He received his MBA from the University of Chicago Booth School of Business.
Important information:
This content is intended as educational only and should not be interpreted as specific recommendations or investment advice. Investors should make investment decisions based on their unique investment objectives and financial situation.
Opinions are as of the date of this report and subject to change.
Past performance of the markets is not a guarantee of future results.
Before investing in bonds, investors should understand the risks involved, including credit risk and market risk. Bond investments are also subject to interest rate risk such that when interest rates rise, the prices of bonds can decease, and the investor can lose principal value if the investment is sold prior to maturity.