Possible savings scenarios
Retirement goal | Education goal |
|---|---|
| Retire at age 65 with $50,000 in annual income from the portfolio. | Provide $110,000 toward Lillian's education (estimate to cover two years of community college and two years at a public university). |
| Required monthly savings: $1,000 | Required monthly savings: $325 |
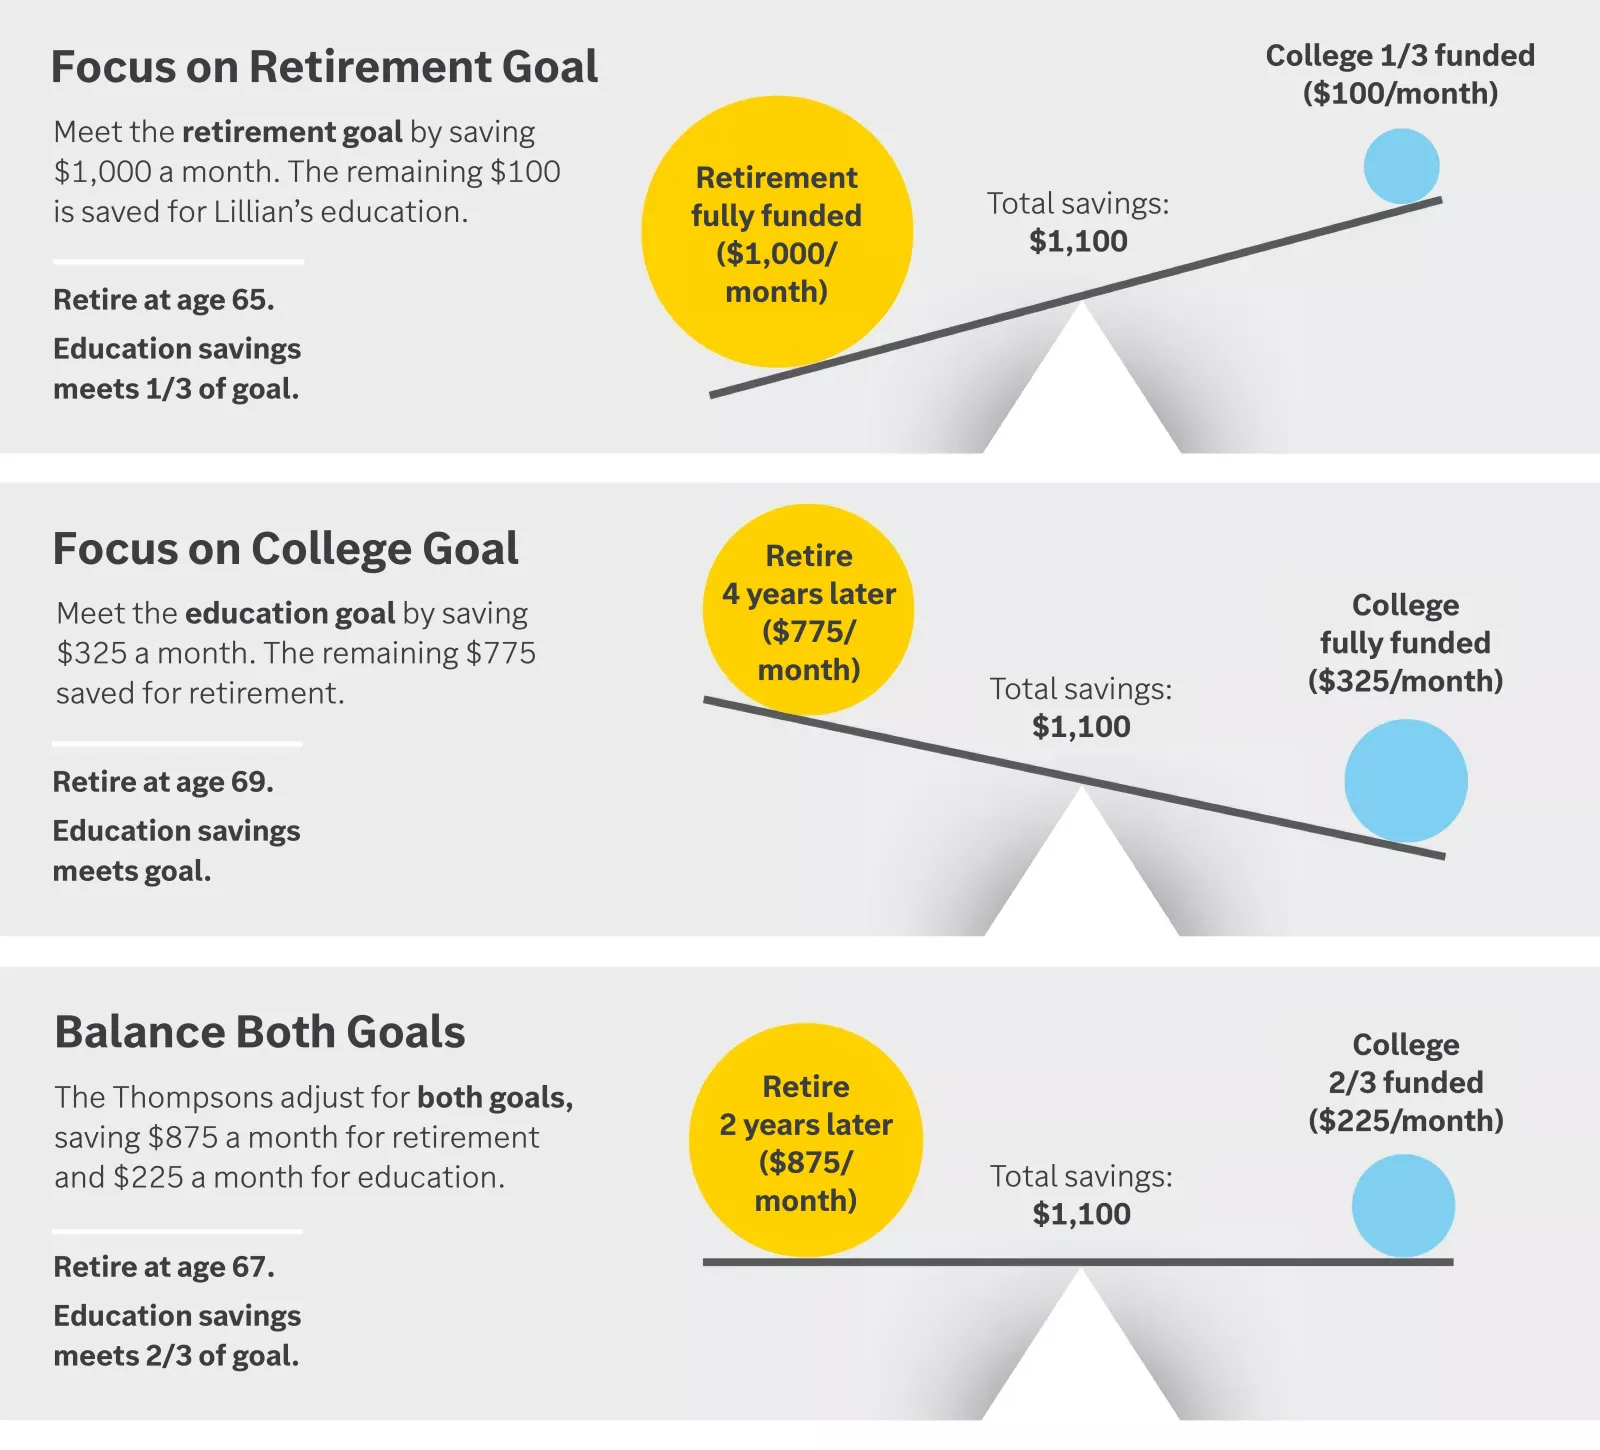
These charts illustrate three savings scenarios. The total monthly savings in each scenario is $1,100, but the difference is how that money is split between retirement and education. In the first scenario, retirement is a priority, so $1,000 goes to that goal while $100 is saved for education. The goal of retiring at age 65 is met, while approximately one-third of the $110,000 education goal is met. In the second scenario, education is a priority, so $325 goes to that, while $775 is saved for retirement. The $110,000 savings goal for education is met, while retirement is delayed until age 69. The third scenario aims to balance retirement and education. So, $875 is saved for retirement and the rest, $225, goes to education. Retirement comes a little later (age 67) and two-thirds of the original $110,000 is saved for education.
Assumptions: Retirement portfolio must provide $50,000 in income, using a 4% initial withdrawal rate. Retirement savings assume 6% annual return. Education savings assume 5.5% annual return through age 8, then 4.5% through age 16, and then 3.5% through age 18. Past performance is not a guarantee of future results. Graphic is for illustrative purposes only and does not reflect any currently available investments. Results rounded to the nearest $5,000.
These charts illustrate three savings scenarios. The total monthly savings in each scenario is $1,100, but the difference is how that money is split between retirement and education. In the first scenario, retirement is a priority, so $1,000 goes to that goal while $100 is saved for education. The goal of retiring at age 65 is met, while approximately one-third of the $110,000 education goal is met. In the second scenario, education is a priority, so $325 goes to that, while $775 is saved for retirement. The $110,000 savings goal for education is met, while retirement is delayed until age 69. The third scenario aims to balance retirement and education. So, $875 is saved for retirement and the rest, $225, goes to education. Retirement comes a little later (age 67) and two-thirds of the original $110,000 is saved for education.
Assumptions: Retirement portfolio must provide $50,000 in income, using a 4% initial withdrawal rate. Retirement savings assume 6% annual return. Education savings assume 5.5% annual return through age 8, then 4.5% through age 16, and then 3.5% through age 18. Past performance is not a guarantee of future results. Graphic is for illustrative purposes only and does not reflect any currently available investments. Results rounded to the nearest $5,000.