Daniel Ladd, CFP® • Senior Analyst, Advice & Planning Research
Katherine Tierney, CFA®, CFP® • Senior Strategist, Advice & Planning Research
Whether it’s fluctuating gas prices or an uncertain job market, 2026 has reminded us how important it is to have a financial strategy that balances stability with goal-oriented growth. This year-end checklist can help you focus on actions that can strengthen your foundation while progressing toward your financial goals.
If you have investable assets of $5 million or more, review additional strategies and tax law changes that may be applicable to you.
1. Year-end review
Self-assessment — Start your review by reflecting on your goals and progress. Consider where you are, how you feel about it and what actions you might want to take next year. It may help to break down your goals into smaller milestones, especially if trying to balance multiple goals at the same time (e.g., building an emergency fund, paying off debt and saving for retirement).
You should also assess whether there have been any changes in your personal, family or employment situation that could impact your goals or progress toward achieving them. Work with your financial advisor to understand the impact and ensure your strategy is aligned.
Estimate your tax situation — Work with your tax professional and financial advisor to understand your tax situation and identify the year-end opportunities in this checklist that make sense for you.
2. Year-end tax considerations
Required minimum distributions (RMDs) — Take RMDs by the deadline to avoid a potential 25% penalty. Generally, anyone age 73 or older must take RMDs from their traditional retirement accounts. Certain inherited IRA owners (including certain inherited Roth accounts) must also take an RMD.
Flexible spending accounts (FSAs) — If possible, use any remaining FSA funds and be sure to submit your claims on time. FSAs are “use it or lose it” accounts, meaning you generally lose any funds unused by year-end or unclaimed by your plan’s deadline.
Roth conversions — If your marginal tax bracket is lower than usual or you expect to be in a higher bracket in retirement, consider converting funds from a pretax retirement account to a Roth account. Keep in mind that a Roth conversion is a taxable event. You’ll want to consult your tax professional and financial advisor to see if this is right for you based on your goals and preferences, current savings mix, time horizon, and current and future tax rates.
Tax-loss harvesting — Review your taxable accounts to identify assets with unrealized losses for potential loss harvesting opportunities. Recognizing capital losses can allow you to offset capital gains recognized throughout the year, including long-term capital gain distributions from mutual funds. Any excess capital losses are next used to reduce ordinary income by up to $3,000. The remaining losses are carried into future years to offset future capital gains.
3. Accelerate progress toward your savings goals
Health savings account (HSA) contributions — Consider increasing contributions to your HSA for you and your family, especially since unused balances carry over from year to year (unlike with an FSA). If you don’t already have an HSA, explore whether you’re eligible for one. Eligible contributions provide an income tax deduction, earnings will generally grow tax free, and distributions will ultimately be tax-free if used for qualified medical expenses. These “triple tax” benefits make an HSA an incredibly valuable addition to your financial tool kit.
Retirement contributions — Consider increasing your retirement contributions and review your mix of pretax and after-tax savings to determine whether you should adjust where you’re saving. Doing so can help you progress on your retirement goals and potentially save on taxes now or in retirement.
529 plan contributions — If saving for education is a goal, consider opening a 529 plan or increasing contributions if you already have one. 529 distributions used for qualified education expenses are federally tax-free. Contributions may also provide you with a state tax benefit. If the beneficiary ends up with an account balance, you have multiple options for these funds. Your financial advisor can review them with you.
4. Maximize your impact
If you want to give to others, explore the following strategies to help you maximize your impact:
Qualified charitable distributions (QCDs) — If you’re 70½ or older, you may be able to exclude up to $111,000 from your adjusted gross income (AGI), regardless of whether you itemize deductions. QCDs are distributions made directly to a qualified charity from your IRA. They can satisfy your IRA RMD (if you have one), which generally results in a lower AGI. A lower AGI can reduce your income taxes and help you save on other AGI-based costs, like taxes on Social Security benefits and Medicare premium surcharges. This amplified impact and their exclusion from the 0.5% deduction floor (discussed next) makes QCDs an attractive giving strategy.
Charitable donations — If you plan to make charitable donations, be aware that the tax rules changed this year. Here’s what you should know:
- If you take the standard deduction, a new deduction is available to you. You can deduct up to $1,000 of cash charitable donations ($2,000 if filing jointly). These donations must be made to a qualified charitable organization, which excludes donor-advised funds (DAFs).
- If you itemize your deductions, you can only deduct the aggregate donations that exceed 0.5% of your AGI, up to the applicable limit. This means you won’t be able to deduct as much of your donations as you have in the past. Work with your tax professional and financial advisor on strategies to reduce the floor’s impact, which may include QCDs or bunching donations into a single year.
Annual gifts — In 2026, you can make a $19,000 gift per donee without using your federal estate and gift tax exemption. If you and your spouse are eligible to gift-split, together you can gift up to $38,000 per donee per year. You can also make payments for tuition and medical expenses directly to providers on someone’s behalf without using the annual exclusion or lifetime exemption.
Take advantage of free money — If you added a child to your family who was born in 2025 or 2026, open a 530A Trump account and elect to receive the one-time $1,000 government contribution. It’s free money. Some employers, philanthropists and nonprofit organizations have also pledged seed contributions to qualified children. If you want to contribute to your child’s retirement yourself, ensure you’re on track with your own retirement goals first. Then, work with your financial advisor to explore your options.
5. Monitor your long-term strategy
While the following actions don’t have specific deadlines, we suggest you perform them periodically and after major life events to help keep your strategy on track.
Portfolio balance and diversification — Review your portfolio annually to ensure it’s still aligned with your goals, time horizon and comfort with risk. If you need to rebalance or diversify, you could employ the above items, such as additional contributions, tax-loss harvesting and RMDs, to help minimize additional taxes.
Expecting the unexpected — To help protect your goals, review your protection strategy every five years or sooner if you experience a meaningful change in circumstances. This could include a change in your family, health, home, employment or financial situation. You should aim to have three to six months’ worth of total expenses in an emergency fund and adequate insurance coverage. Be sure your protection keeps pace with your expenses, income and asset values, which may mean additional contributions to your emergency fund or increasing insurance coverage.
Review your beneficiaries, asset titling and estate plan — Review asset titling and beneficiary designations for any new accounts, real estate and vehicles each year. Review your full estate plan and titling for all assets every three to five years or sooner if your circumstances change or a change in estate law occurs. It’s important to follow your attorney’s recommendations on how to title your assets appropriately and to keep up-to-date beneficiaries to ensure your assets pass according to your wishes. If you make significant changes to your estate plan, consider sharing them with your beneficiaries.
Important deadlines to note
Many of these actions must be completed by certain dates. Please note, it may take time to process requests and changes, so plan to act sooner rather than later.
The amounts shown in the following table apply per person unless otherwise indicated.
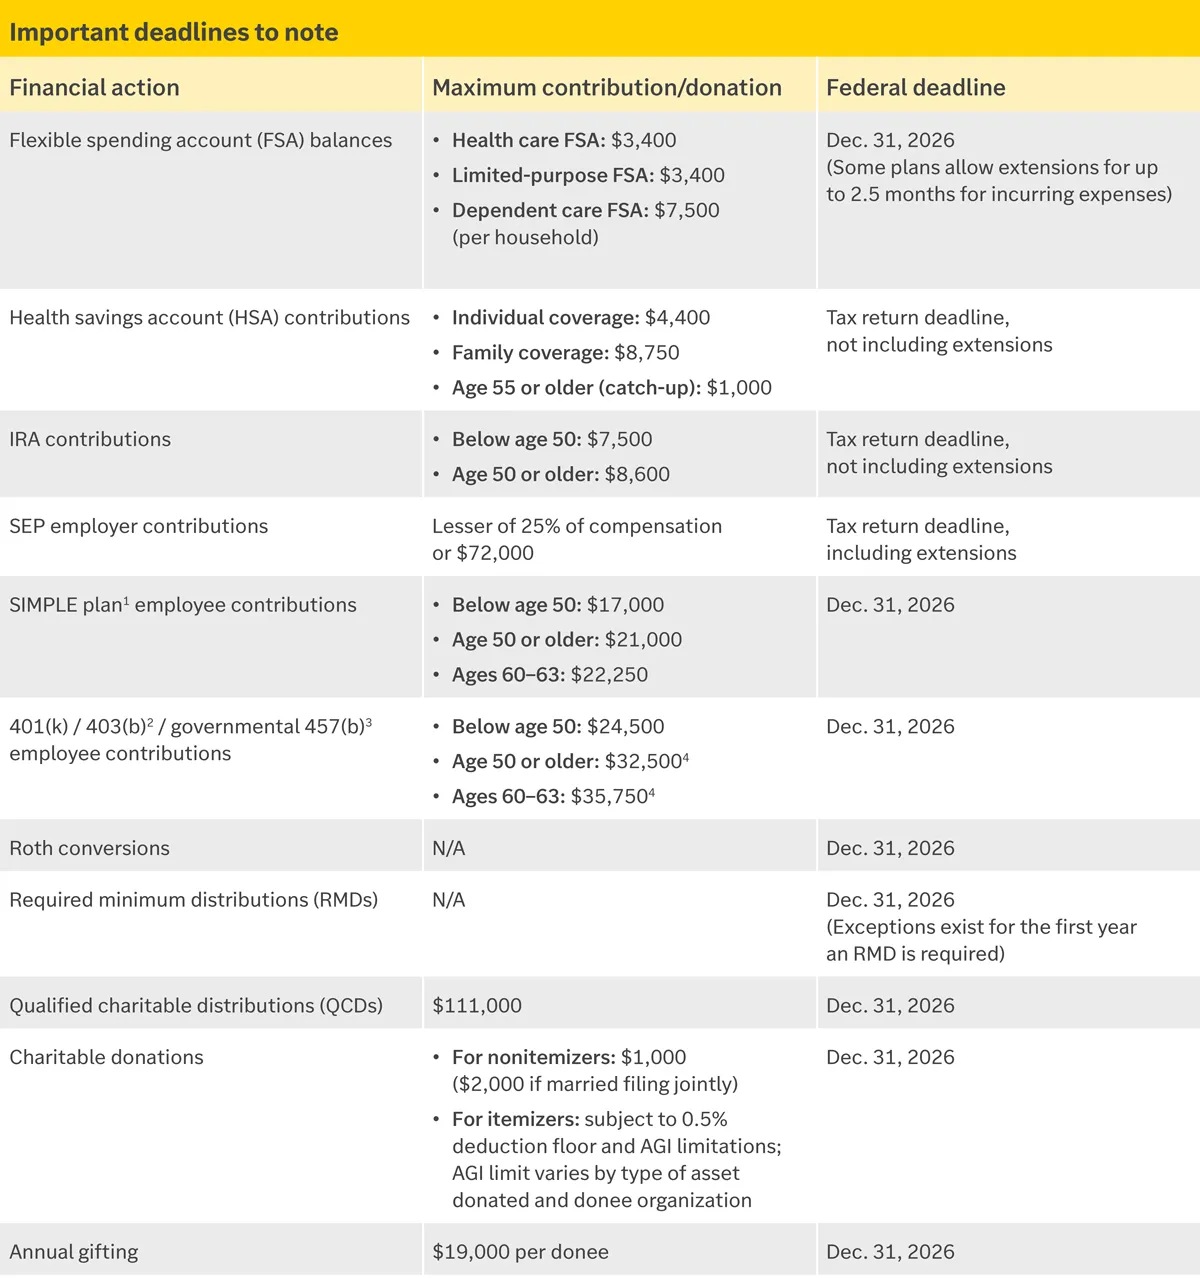
1 Certain plans can contribute 110% of contribution limits. Consult your plan administrator.
2 Additional service-based catch-up contributions may be permitted. Consult your plan administrator.
3 Limit applies to combined employee and employer contributions.
4 If your wages exceeded $150,000 last year, you’re only able to make Roth catch-up contributions.
Important information:
Edward Jones, its employees and financial advisors cannot provide tax or legal advice. You should consult your attorney or qualified tax advisor regarding your situation.
This content is intended as educational only and should not be interpreted as a specific recommendation or investment advice. Investors should make investment decisions based on their unique investment objectives and financial situation.