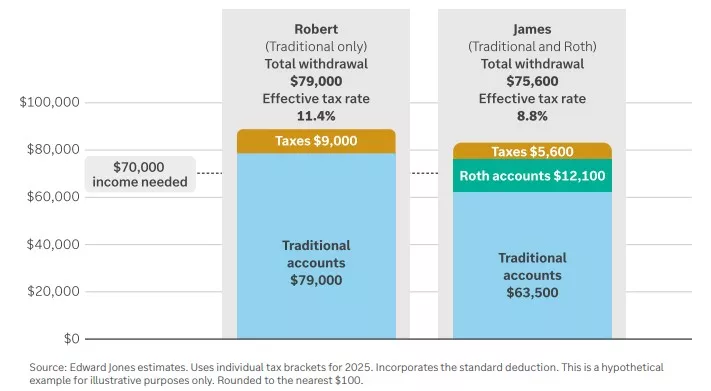
The chart above shows the differences in Robert’s and James' withdrawal strategies and their effective tax rates.
Robert will have to withdraw $79,000 from his traditional accounts to meet his $70,000 spending need and the $9,000 he’ll owe for taxes on the withdrawal. Robert’s effective tax rate is 11.4%.
James withdraws $63,500 from his traditional accounts and $12,100 from his Roth accounts to meet his $70,000 spending need and the $5,600 he’ll owe for taxes on the traditional account withdrawal. James' effective tax rate is 8.8%.
Important information:
Edward Jones, its employees and financial advisors cannot provide tax or legal advice. You should consult your attorney or qualified tax advisor regarding your situation.
This content is intended as educational only and should not be interpreted as specific recommendations or investment advice. Investors should make decisions based on their unique investment objectives and financial situation.