Key takeaways:
- The 2027 COLA is 3.6%, materially above the 20-year average.
- COLA applies even if you delay claiming benefits.
- Medicare Part B premiums may offset some of the increase.
- A strategic use of COLA can support your portfolio's longevity.
The Social Security Administration (SSA) announced a 2027 cost-of-living adjustment (COLA) for Social Security benefits of 3.6%. The COLA was above the 20-year average of 2.6%.
The COLA is based on the rate of inflation as measured by the Consumer Price Index for Urban Wage Earners and Clerical Workers, known as the CPI-W. The 2027 increase reflects the change in the average CPI-W reading from the third quarter of last year to the third quarter of this year.
Social Security recipients will see the COLA reflected in their January benefit payment. However, if your Medicare Part B premium is deducted from your Social Security payment, an increase in your premium will likely offset some of the increase in your Social Security benefit.
Importantly, you’ll still receive the COLA even if you delay claiming Social Security benefits. Each year’s COLA is applied to your benefit base, so any increases you would have received are included in your benefit when you ultimately claim.
COLA’s impact on your retirement strategy
The Social Security COLA is a valuable, yet often overlooked, component of retirement planning. Because this year’s COLA is applied to the benefit you received last year, it compounds over time and can meaningfully raise lifetime benefits. This increase can help retirees keep pace with rising costs throughout retirement.
Depending on your spending plans, the COLA may allow you to maintain or even reduce how much you need to withdraw from your investment portfolio. Even small reductions in your withdrawal rate can meaningfully benefit your portfolio’s longevity.
If you don't need the COLA to pay for higher expenses, you can put those extra dollars to use by adding them to your cash reserves. Cash reserves can help you prepare for potential market declines by helping meet your spending needs while giving your portfolio time to recover.
We generally recommend retirees maintain:
- 12 months’ worth of portfolio withdrawals in cash in a separate account for spending
- Three to five years’ worth of portfolio withdrawals in a short-term fixed-income ladder
- Three to six months’ worth of spending in an emergency fund
Other Social Security adjustments
In addition to the COLA, the SSA announced several annual program adjustments that may affect workers and retirees.
- Maximum taxable earnings amount — $192,300
- Earnings limit for retirees who file before reaching full retirement age (FRA) — $25,560 for years before reaching FRA; $67,920 for the year a retiree reaches FRA
Social Security COLA: A look back
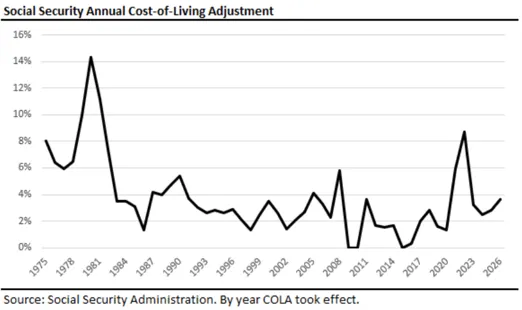
This chart provides the annual cost-of-living adjustment (COLA) for Social Security from 1975 through 2027, by the year the COLA took effect. The highest annual COLA during this period was 14.3%, and the lowest was 0%.
This chart provides the annual cost-of-living adjustment (COLA) for Social Security from 1975 through 2027, by the year the COLA took effect. The highest annual COLA during this period was 14.3%, and the lowest was 0%.
*The Social Security Administration has additional information you may find useful. This information provided by the Social Security Administration is provided as a courtesy and is intended for informational purposes only. Edward Jones makes no representations concerning the content of this site.